How American Express benefits retailers
Increase your average receipt amount with American Express and attract new customers with high purchasing power.

Eine freundlich lächelnde Unternehmerin in dunkler Schürze steht mit Tablet an der Glastür ihres stilvollen Geschäfts, dahinter verschwimmen Blumen zu einer eleganten, einladenden Kulisse. Das Bild veranschaulicht wie Händler und Akzeptanzpartner mit American Express ein hochwertiges Markenerlebnis schaffen: persönlicher Service, digitale Effizienz und die Chance, premium-orientierte Kundinnen und Kunden im richtigen Moment zu erreichen. Es steht für Vertrauen, Komfort und geschäftliche Vorteile durch die Akzeptanz von American Express.

At a glance:
why Amex makes sense for merchants
Accepting American Express can help retailers reduce shopping cart abandonment, reach high-spending customers, and increase sales – especially when dealing with high-end product lines, international customers, and in B2B business.
Alongside debit cards, credit cards and mobile wallets, American Express is part of a customer-centric payment strategy that makes completing a purchase as easy as possible. The transaction fee starting at 1.95 percent for small merchants should be weighed against the potential for increased sales, additional impulse purchases, and the ability to attract premium and corporate customers.
Shopping should be hassle-free: when the payment determines whether a purchase is made
The payment isn’t just a necessary step at the end of the sale – it is part of the shopping experience. It can determine whether interest actually turns into revenue. If a merchant has to explain that certain methods of payment aren’t available at the checkout, it creates friction precisely when the purchase should be made.
After all, spontaneous purchases in particular are often emotional: If there isn’t enough cash in a customer’s wallet or their preferred card isn’t accepted, "I’ll just grab this" quickly turns into "I’ll think about it for now."
Retailers who rely on customers to adapt to the available payment options are missing out on opportunities for increased sales and new target groups. After all, the Swiss payment landscape has become extremely diverse. While cash remains important in brick-and-mortar stores, debit cards, credit cards – such as those from American Express – and mobile payments are being used more and more frequently.
And these payment options only appear to involve higher costs for merchants at first glance: A recent study on point-of-sale payments in the economy concluded that cash incurs the highest resource costs, due in part to front-office and back-office operations, cash management, and opportunity costs.
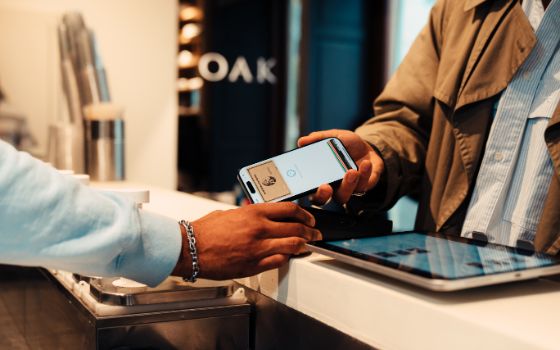
According to the Swiss Payment Monitor 1/2026, credit cards now account for 25.3 percent of in-store transactions in Switzerland – either directly or indirectly via a mobile wallet in which a credit card is stored, such as Apple Pay or Google Pay.

Customer segment analysis: Who buys from you?
A good payment strategy is based on a thorough understanding of your customer base. In Switzerland, this can generally be divided into three groups.
Everyday shoppers
For everyday shopping, speed and habits are key. For smaller amounts, many customers use a debit card or payment apps on their smartphones and smartwatches. If you offer contactless payment in your store and position the terminal in a visible and intuitive location, you’ll make it easy for this group.
International travelers
International visitors don’t want to have to search for an ATM first or be told at the checkout that their card isn’t accepted. Especially in tourist areas, city centers, airports and border regions, accepting international cards is part of the service promise. It removes an unnecessary barrier to purchase, regardless of whether someone pays with a physical card or a digital wallet.
High-spending customers and loyal regulars
For purchases requiring consultation, luxury goods, home furnishings, electronics, watches, eyewear and high-end gifts, the payment method is part of the customer’s expectations. This clientele often uses credit and premium cards not only for financing but also for insurance benefits, travel perks, or rewards programs.

Das Gübelin Logo auf weissem Hintergrund steht als klares Signal für Stil, Vertrauen und Premium-Qualität im Netzwerk der American Express Akzeptanzpartner. Als visuelles Element zu redaktionellen Inhalten über die Vorteile für Händler zeigt das Bild, wie eine renommierte Luxusmarke American Express als komfortable, sichere und kundenorientierte Zahlungslösung integriert. So vermittelt es Exklusivität, Kaufkraft und die Relevanz starker Partnerschaften für anspruchsvolle Kundinnen und Kunden.

Das Markant-Logo auf weissem Hintergrund steht als klares Signal für Stil, Vertrauen und Premium-Qualität im Netzwerk der American Express Akzeptanzpartner. Als visuelles Element zu redaktionellen Inhalten über die Vorteile für Händler zeigt das Bild, wie eine renommierte Marke American Express als komfortable, sichere und kundenorientierte Zahlungslösung integriert. So vermittelt es Exklusivität, Kaufkraft und die Relevanz starker Partnerschaften für anspruchsvolle Kundinnen und Kunden.

Das Tennis Factory-Logo auf weissem Hintergrund steht als klares Signal für Stil, Vertrauen und Premium-Qualität im Netzwerk der American Express Akzeptanzpartner. Als visuelles Element zu redaktionellen Inhalten über die Vorteile für Händler zeigt das Bild, wie eine renommierte Marke American Express als komfortable, sichere und kundenorientierte Zahlungslösung integriert. So vermittelt es Exklusivität, Kaufkraft und die Relevanz starker Partnerschaften für anspruchsvolle Kundinnen und Kunden.

Das Logo von xess + baba auf weissem Hintergrund steht als klares Signal für Stil, Vertrauen und Premium-Qualität im Netzwerk der American Express Akzeptanzpartner. Als visuelles Element zu redaktionellen Inhalten über die Vorteile für Händler zeigt das Bild, wie eine renommierte Marke American Express als komfortable, sichere und kundenorientierte Zahlungslösung integriert. So vermittelt es Exklusivität, Kaufkraft und die Relevanz starker Partnerschaften für anspruchsvolle Kundinnen und Kunden.
Offering American Express as a payment option: a strategic advantage in retail
Some smaller businesses still view American Express with hesitancy. They’re on the wrong track – especially businesses with a range of premium products, an international customer base, and B2B sales.
Higher receipts from customers with strong purchasing power
American Express customers in Switzerland spend about 20 percent more than other credit card users. This figure is a key indicator for merchants: Accepting American Express can provide access to a target group with above-average spending power.
For fashion, furniture, consumer electronics, beauty and design products, wine or luxury goods, even just one additional sale per week can more than offset the acceptance fee of 1.95 percent per transaction. The key factor in this calculation is the contribution margin from those sales that would not have occurred without American Express acceptance.
The reward effect: Points provide an additional incentive to buy
With participating American Express credit cards, cardholders collect Membership Rewards points on purchases, which can be redeemed for attractive rewards. This does not change the need for a product, but it can influence the choice between two comparable providers.
Therefore, if you accept American Express payments in your store, you give customers one less reason to postpone a purchase or go to a competitor.

Corporate Cards for B2B business
Anyone who sells office supplies, IT accessories, corporate gifts, wine, furniture, work equipment, or high-quality services is also likely to have corporate customers. American Express positions its Corporate Cards and Business Cards for everyday business expenses, purchases and reimbursements. These cards also offer companies greater transparency and reliable reporting.
For merchants, this means that failing to accept a Corporate Card doesn’t just jeopardize a one-off purchase, but also a long-term business relationship. With orders on account or when employees pick up orders in particular, the staff team should know which cards are accepted and how to serve corporate customers as efficiently as possible.

Increase visibility through free marketing
As a retailer in Switzerland, accepting American Express provides you with greater reach. You benefit from free marketing through your presence at American Express Selects.
At American Express Selects, you can showcase your business with a limited-time special offer such as a discount or a voucher. The Selects platform attracts more than 360,000 visitors annually. Of these, 260,000 American Express members have subscribed to the monthly newsletter, which has an average read-rate of 60 percent.




Cost-benefit analysis: why it pays to accept American Express
Small merchants with annual American Express Card turnover of up to CHF 100,000 pay transaction fees starting at 1.95 percent – a clear and uniform all-inclusive rate. These fees should not be viewed in isolation, though, as other factors also play a role:
If customers pay with cash instead, you also incur costs. Cash transactions also entail the workload surrounding cashing up, depositing funds, transporting money, and providing change. Discrepancies and security risks can also arise.
And, of course, so-called opportunity costs play a role: In some industries, the revenue and profit margins lost from purchases that aren’t completed due to a lack of payment options can be significant. Therefore, accepting American Express is particularly worthwhile if your target audience uses American Express or has larger-than-average shopping carts.
The decision should therefore be data-driven. Try out acceptance for up to three months and analyze the following things:
- Amount and revenue of American Express transactions
- Average amount paid per payment method
- Return rate
- Percentage of international customers
- Turnover trends in higher-priced categories
- Feedback from the staff team and customers
That’s how a fee-related issue becomes a business decision.
Benefits for retailers as American Express acceptance partners
Payment is a sales tool, not just infrastructure
Contemporary retail doesn’t just compete on product selection, price and customer service. It also competes on the ease of completing a purchase. By offering debit cards, credit cards, mobile wallets and appropriate local payment methods in your store, you create better conditions for impulse purchases and repeat business – and thus for higher turnover.
American Express is a must, especially for merchants with an international customer base, high-quality product assortments, or B2B potential.
Frequently asked questions and answers
American Express can bring your business additional, often high-spending customers, higher transaction values, and a stronger position in the B2B segment.
With American Express, merchants pay a flat fee starting at 1.95 percent per transaction, as long as annual American Express card sales do not exceed CHF 100,000.
If you’re considering welcoming American Express cardholders to your business, you can submit your contact information via the merchant contact form, and we’ll get back to you shortly. Or you can call us directly at 044 659 64 44 (Monday through Friday from 8 a.m. to 6 p.m.) to have your questions answered as quickly as possible.